Honda Restricted Use Loan (RUL)
A Restricted Use Loan from Honda Financial Services helps you spread the cost of your motorcycle, accessories and clothing. You own the goods at the start of your finance agreement and have fixed repayments over an agreed term.
Who is RUL for?
RUL may be for you if you would like to spread the cost of accessories and clothing, as well as your motorcycle and you want ownership as soon as you take delivery.
How RUL works
Step 1
Choose the motorcycle, clothing and accessories you want and agree how much deposit you'd like to put down.
Step 2
You can then adjust the term to best suit your ideal monthly budget, anywhere between twelve and sixty months. For any clothing and accessories that you decide to fund using RUL, the term of the agreement is anywhere between twelve and thirty-six months.
Step 3
The rest of the cost of the motorcycle, clothing or accessories, plus interest, is paid in equal fixed monthly payments.
A Restricted Use Loan provides you with instant ownership of the goods, as you use the funds to purchase them. You then pay all the agreed loan instalments until the loan value and interest has been paid in full.
End of contract options
With a Restricted Use Loan agreement you will be the legal owner of the motorcycle once you take delivery.
Once you pay the final payment, your agreement with us comes to an end.
You may choose to part exchange your motorcycle.
Key Features
-
If you use RUL to fund your motorcycle, there are no mileage limits as part of the finance agreement.
-
You take ownership of all the goods purchased at the start of your finance agreement. unlike a PCP or HP agreement our RUL is not secured against the motorcycle.
-
Clothing and accessories not linked to the motorcycle can be funded using RUL. There is a maximum term of 36 months if funded separately to the motorcycle.
-
The Total Amount Payable (TAP) is likely to be less than if you funded your motorcycle with a PCP over the same term.
-
14 day right to withdraw.
-
Can partially or fully settle early (subject to the terms of your agreement).
Key Considerations
-
With RUL there is no deferred payment (Guaranteed Future Value), so you may pay more a month compared to PCP over the same term.
-
You have none of the Voluntary Termination or Repossession rights, which apply to HP and PCP under the Consumer Credit Act (CCA)
Related FAQs
RUL is available on used Honda motorcycles too
RUL can be used to buy a used motorcycle from a Honda dealer, along with accessories and clothing. Your dealer will be able to help you choose the right motorcycle and the right finance product for you.
About us
Welcome to Miles Kingsport Ltd, the only place for Honda motorcycles and scooters across East and North Yorkshire. With in excess of 50 years dealing with the number one brand we are the Dealership to trust for all your motorcycle, clothing, parts, accessory and servicing needs.
Opening Hours
Monday - Friday 8:30am -5:00pmSaturday 8:30am - 5:00pm
Sunday - Closed
Bank Holiday Monday's & Good Friday - Closed
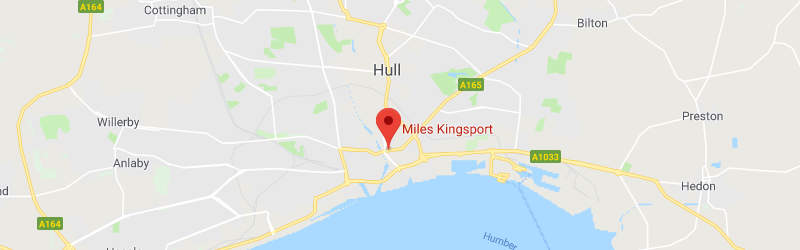
Find us
We are authorised and regulated by the Financial Conduct Authority, registration number 654936.
“We are a credit broker and not a lender. We can introduce you to a limited number of lenders and their finance products which may have different interest rates and charges. We are not an independent financial advisor. We will provide details of products available from the lenders we work with, but no advice or recommendation will be made. You must decide whether the finance product is right for you. We do not charge you a fee for our services. Whichever lender we introduce you to, we will typically receive commission from them (either a fixed fee or a fixed percentage of the amount you borrow). The lenders we work with could pay commission at different rates. However, the amount of commission we receive from a lender does not have an effect on the amount you pay to that lender under your credit agreement.” We will disclose the amount of commission we receive before you sign the agreement.
Complaints procedure.
We take all complaints seriously.
Our process for dealing with complaints received by us will differ depending on what the complaint is about.
1. Products regulated by the Financial Conduct Authority (FCA)
We will treat as a FCA regulated product complaint relating to credit broking or insurance product (Regulated Complaint) any oral or written or email expression of dissatisfaction, whether justified or not, from, or on behalf of, a person about the provision of, or failure to provide, a financial service, which alleges that the complainant has suffered (or may suffer) financial loss, material distress or material inconvenience.
2. Goods and non-financial services
All other complaints regarding goods or non-financial services supplied by us will be treated as a general complaint.
Process for all complaints
Many concerns can be dealt with straight away but sometimes it is necessary for us to look into the matters you have raised in more detail. Please address all complaints to our Managing Director in the first instance to our business address by post, or via the general enquiry form online.
The responsible department manager or director will contact you to attempt to resolve the concern.
If the concern has not been resolved within 14 days it will be automatically escalated back to the Managing Director. When a concern is believed to have been resolved by the responsible manager or director, they will submit the concern for closure via the Managing Director.
You may raise or discuss your concern with our Manging Director at any stage.
Process for general complaints
After the process above, if we are unable to resolve your complaint to your satisfaction, then we will provide details of certified Alternative Dispute Resolution providers that you may contact.
Process for Regulated Complaints
In addition to the process above, our management team will also review all regulated Complaints and we have a slightly more formal process as follows:
• Promptly following receipt of your complaint
Any regulated Complaint that has not been resolved straight away will be recorded by our management team and we will send you a letter to acknowledge your concerns.
If we believe that another firm or company is responsible for the matters to which your complaint relates and is therefore best placed to resolve it, we may forward your complaint to them to investigate. If we do so, we will write to you to let you know and will give you the name of the firm or company to which we are forwarding your complaint.
• Within eight weeks from receipt
Unless covered by the second paragraph below, we will aim to have completed our investigation and provide you with our final response in relation to your complaint within eight weeks of receipt of your complaint. If we cannot provide you with our response within eight weeks, we will write to you explaining why this is the case and indicate when a response will be sent to you. You will also be advised of your right to take the matter to the Financial Ombudsman Service should you be dissatisfied with the outcome of our investigation and our final response.
